
Operation Twist
Abstract
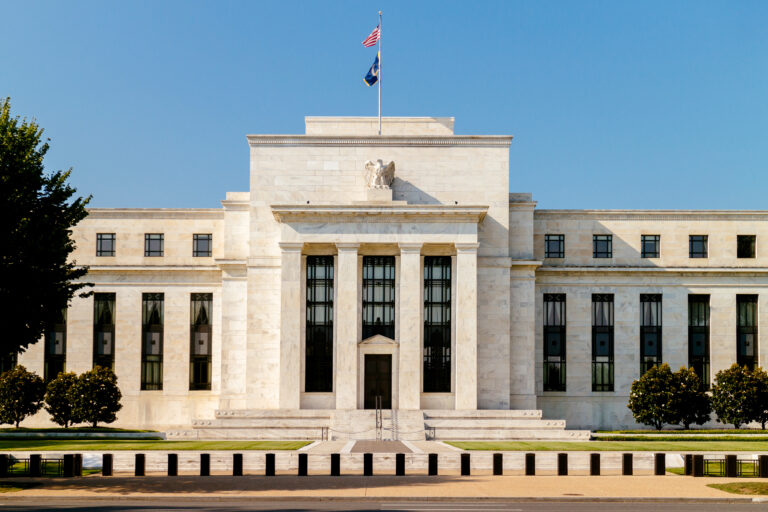
The almost comical sounding term “Operation Twist” has been creeping into the financial media since last December as Federal Reserve officials and market commentators discussed innovative ways to revive the stagnant economy. This phrase became a household name on September 21st, when the Federal Open Market Committee (FOMC) decided to simultaneously buy $400 billion of U.S. Treasury securities with maturities ranging from six to 30 years and sell an equal amount of securities with maturities of three years or less. While the effectiveness of this maneuver on the labor market remains a hot point of contention, its impact on short-term securities has been somewhat overlooked. We believe corporate treasurers may benefit from the “Twist” in the form of some yield relief, although the near- to medium-term yield outlook remains clouded.
Operation Twist 2.0
No, the Fed is not twisting arms to create jobs. Instead, Operation Twist refers to a tactic that the Federal Reserve has employed in the past with the goal of lowering long-term interest rates and spurring growth by influencing the shape of the term structure of interest rates, commonly known as the “yield curve.” In this maneuver, the Fed buys long-dated Treasury notes and bonds while simultaneously selling short-dated Treasury bills and notes. By creating demand for the long-dated notes and bonds, the Fed hopes to push up prices, which, in turn, would lower the yields on the long-end of the yield curve. The opposite effect on the short-end of the yield curve would likely raise yields, hence the Twist.
Operation Twist is not a new concept. The Fed introduced Operation Twist in the early 1960s (when Chubby Checker and the dance known as The Twist were all the rage) to spur economic growth during an economic recession. Operation Twist was back in the spotlight in November 2002, after then Fed Governor Ben Bernanke mentioned the 1960s Fed move to combat the threat of deflation in a speech he delivered to the National Economists Club . Governor Bernanke concluded that “academic opinion on the effectiveness of Operation Twist is divided;” remarks that earned him the nickname “Helicopter Ben.” In any case, this episode was rather small in scale, did not involve an explicit announcement of target rates, and occurred when interest rates were not close to zero.”
Given this nearly forgotten piece of history, the recent Fed decision, dubbed by some as Quantitative Easing 2.5, actually is Operation Twist 2.0. The key difference, as Mr. Bernanke pointed out nine years ago, is that interest rates were much higher in the 1960s. Furthermore, Operation Twist 2.0 follows two consecutive rounds of quantitative easing, which has injected massive amounts of liquidity into the banking system. This is why sharp disagreement over the policy’s effectiveness has been prevalent ever since the idea was floated last December.
DOWNLOAD FULL REPORT
Our research is for personal, non-commercial use only. You may not copy, distribute or modify content contained on this Website without prior written authorization from Capital Advisors Group. By viewing this Website and/or downloading its content, you agree to the Terms of Use.
Please click here for disclosure information: Our research is for personal, non-commercial use only. You may not copy, distribute or modify content contained on this Website without prior written authorization from Capital Advisors Group. By viewing this Website and/or downloading its content, you agree to the Terms of Use & Privacy Policy.